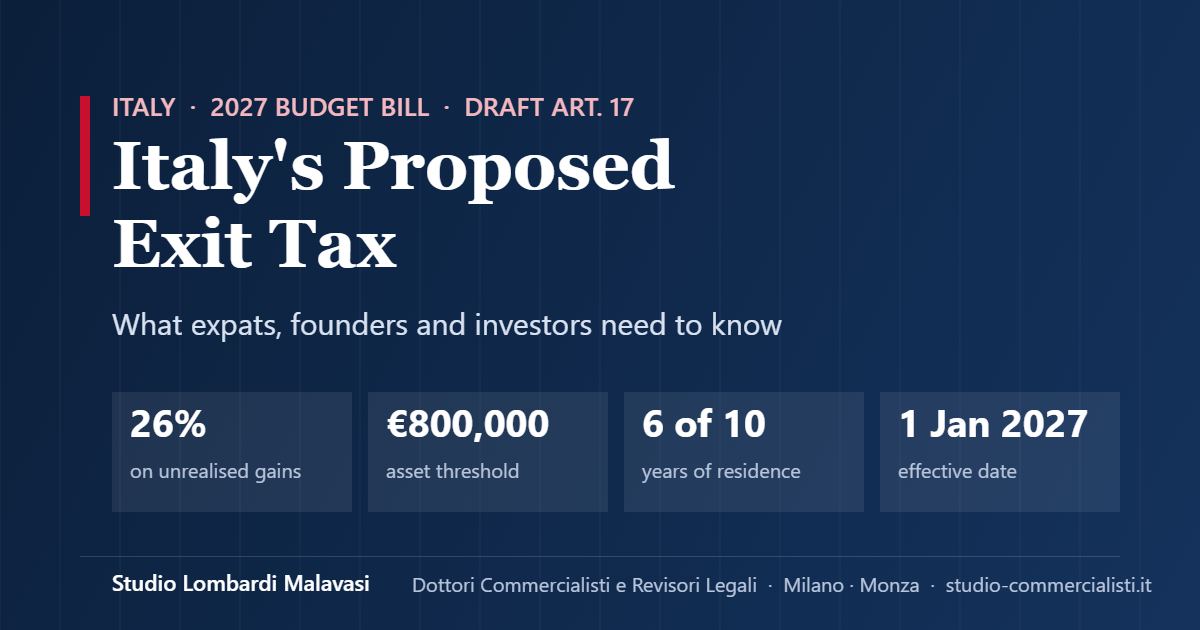

Draft Article 17 of the 2027 Budget Bill would, for the first time, tax individuals on unrealised capital gains when they move their tax residence out of Italy. Here is what the text says, who is affected, and what is still unclear.
The short version
On 28 October 2026 the Italian Council of Ministers approved the 2027 Budget Bill (Disegno di legge di bilancio 2027). Among the measures that received little advance publicity is Article 17, which introduces a new Article 307-bis into the new Italian Income Tax Code (the recodified TUIR, Legislative Decree 117/2026, in force from 1 January 2027).
The provision is an exit tax for individuals. Italy has long taxed companies and entrepreneurs that move abroad on the latent gains in their business assets (historically Article 166 TUIR). Until now, however, a private individual could leave Italy with a portfolio full of unrealised gains and pay nothing to the Italian Treasury on departure. The draft closes that gap.
The bill is now before the Chamber of Deputies. Parliament must approve the budget by 31 December 2026, and amendments are expected in the second half of November. Everything below describes the draft as published and may change.
Who would be caught
Three cumulative conditions trigger the tax:
- Long-term residence. You must have been tax resident in Italy for at least six of the ten tax periods preceding the transfer. Nationality is irrelevant: an Italian citizen returning home after a career in Milan and a British or American expat who settled in Tuscany eight years ago are treated identically.
- Loss of Italian taxing rights. The transfer must mean that Italy loses the power to tax the future disposal of the assets concerned. For most financial assets held by a non-resident this is the normal outcome under domestic law and treaties.
- The €800,000 threshold. The total market value (valore normale) of the relevant assets, measured on 31 December of the year before the loss of residence takes effect, must be at least €800,000.
The threshold is a cliff, not an allowance. A portfolio worth €790,000 is outside the regime; one worth €810,000 brings every euro of latent gain into charge, not just the excess over €800,000.
The rules would also extend to società semplici, equivalent non-commercial entities and non-commercial bodies that transfer abroad.
Which assets are covered
The draft refers to assets whose disposal would generate “other income” under Article 76(1)(d) to (i) of the new TUIR (the old Article 67). In practice this means:
- qualified and non-qualified shareholdings, including quotas in Italian S.r.l.s;
- bonds and other securities;
- units in investment funds and ETFs;
- derivatives;
- foreign currencies, precious metals and receivables;
- crypto-assets.
Real estate is excluded, as are dividends and interest, which are not capital gains. Regulated occupational pension schemes also appear to fall outside the regime, although foreign pension wrappers and unit-linked policies will need case-by-case analysis.
How the tax is calculated
The taxable base is the sum, asset by asset, of the positive differences between market value at the valuation date and the tax-recognised cost. Two features of the draft are particularly harsh:
- Losses are ignored. A holding showing a €250,000 loss does not reduce the tax on another holding showing a €200,000 gain. The portfolio may be down overall and tax is still due.
- Pre-arrival gains are included. There is no “step-up” to the value of the assets on the day you became Italian resident. Someone who arrived with a portfolio already carrying large gains would be taxed by Italy on appreciation that occurred before they ever set foot in the country.
The rate follows the ordinary rules for financial income: 26% in most cases. Italian and equivalent government bonds keep their preferential treatment by being counted at 48.08% of value (effective 12.5%). Whether the 33% rate recently introduced for crypto gains carries over to the exit charge is not clear from the text.
A worked example. A German consultant has lived in Turin for nine years and holds a listed-share portfolio worth €1,300,000 on 31 December 2026, acquired for €800,000. She moves to Lyon in 2027. Latent gain: €500,000. Exit tax at 26%: €130,000.
When and how it is paid
The default rule is simple and demanding: the tax is due within 180 days of the loss of residence taking effect.
A deferral is available, but only for moves to:
- another EU Member State, or
- a non-EU state that has agreements with Italy on exchange of information and on assistance in tax recovery equivalent to Directive 2010/24/EU.
Deferral is not free. The taxpayer must:
- pay 50% of the tax up front, within the same 180 days, and
- provide an “adequate guarantee” for the balance (the draft does not say what counts as adequate).
Our German consultant would therefore pay €65,000 in cash within six months of leaving and lodge security for the other €65,000.
The deferral runs for five tax periods for EU moves and ten for other qualifying countries. During that window:
- if an asset is sold, tax is due on the lower of the gain accrued at departure and the gain actually realised, with the advance credited;
- if an asset is gifted, or transferred to a controlled company or to close family members, tax is due on the full gain accrued at departure;
- if an asset is still held at the end of the deferral period, passes on death, or the taxpayer returns to Italian residence within the window, no tax is due on it and any excess advance is refunded.
For moves to a country with no qualifying agreement, there is no deferral: the full amount is payable within 180 days, on gains that may never be realised.
Timing: why 2026 matters
The regime applies to transfers of residence effective from 1 January 2027. Italy has no split-year rule in domestic law: residence is assessed for the whole calendar year. Someone who physically leaves in the autumn of 2026 will typically still be Italian resident for 2026 and become non-resident from 1 January 2027, with assets valued at 31 December 2026. In other words, leaving in late 2026 does not automatically avoid the charge.
How much revenue?
Very little. The Technical Report attached to the bill estimates €3.37 million in 2027, €6.74 million a year from 2028 to 2031, and about €3.37 million a year net of refunds from 2032. By way of comparison, that is roughly what eleven new residents pay in a single year under the €300,000 flat-tax regime for high-net-worth newcomers. The measure is better understood as a signal, and as an anti-avoidance backstop, than as a fiscal pillar.
Comparison with France
The design closely follows France’s exit tax (Article 167 bis CGI): same six-of-ten-years test, same €800,000 threshold. The differences are telling. In France, deferral for moves within the EU/EEA is automatic and requires no guarantee, and the tax lapses after two years (five for the largest portfolios) if the assets are not sold. The Italian draft, by contrast, demands a 50% advance and security even for a move from Milan to Paris.
That matters legally. In de Lasteyrie du Saillant (C-9/02, 2004) the Court of Justice of the EU held that France’s original exit tax breached freedom of establishment, and specifically that making deferral conditional on guarantees was itself a restriction. Commentators also point to a pending CJEU case on Poland’s exit tax, in which the Advocate General’s opinion of October 2026 reportedly questions both the taxation of pre-residence gains and the exclusion of latent losses, the two harshest features of the Italian draft. Expect EU-law arguments to feature in the parliamentary debate.
What the draft does not answer
- Which non-EU countries qualify for deferral. Switzerland, the United Kingdom, the United States and the UAE are the obvious questions, and the text names none of them.
- Interaction with Italy’s special regimes. A newcomer under the €300,000 flat tax, or a retiree under the 7% regime for southern Italy, pays little or nothing on foreign gains while resident. Would they face 26% on the same gains on the way out? The draft is silent.
- Couples and jointly held assets. The €800,000 test is per person, but the treatment of joint accounts is not addressed.
- Valuation of unlisted holdings and of long-held assets with poor cost records.
- Transitional protection for people who have already committed to a move.
- Relief in the destination country. Whether your new country of residence will recognise the Italian deemed disposal as a new cost basis depends on its domestic law and on the applicable treaty, something Italy cannot legislate for. Double taxation on the same gain is a real risk.
What to do now
- Establish your residence history. Count the tax periods of Italian residence in the last ten years; the six-year test is the gateway.
- Map your financial assets and their cost. Gather acquisition documentation now, especially for assets bought before you moved to Italy and for crypto, where an unproven cost means a cost of zero.
- Model the 31 December value. If you are near the €800,000 line, year-end market movements decide whether you are inside or outside the regime.
- Plan liquidity. Even with deferral, half the tax is cash within six months, plus a guarantee.
- Check the destination. EU versus non-EU, the treaty position, and how the new country treats your cost basis.
- Do not act on the draft alone. The text will change before 31 December, and an implementing decree from the Ministry of Economy and Finance will fill in essential details.
How we can help
Cross-border moves in and out of Italy are at the heart of our practice. Studio Lombardi Malavasi advises expats, international professionals and foreign-owned businesses on Italian tax residence, the special regimes for inbound workers and new residents, and the coordination between Italian rules and those of the home or destination country. If you are considering a move out of Italy in 2027, or arrived in Italy within the last decade and want to understand your exposure, book a free initial consultation in English or Italian.
This article reflects the draft 2027 Budget Bill as approved by the Council of Ministers on 28 October 2026 and is for general information only. It is not tax advice and will be updated as the parliamentary process progresses.