02.4004.4318
CALL US!
8:30 - 17:30
Mon-Fri

Archivio: Aprile 30, 2026

Italy’s Elective 15% CFC Tax: 2026 Guidance Simplifies Compliance for Multinational Groups

On 31 March 2026 the Italian Revenue Agency issued long-awaited guidance on the elective 15% tax introduced into Italy’s Controlled Foreign Company (CFC) regime by the 2023 international tax reform. The new measure offers Italian-controlled foreign subsidiaries a simplified route to satisfy the CFC effective-taxation test, replacing a notoriously complex calculation with a flat 15% charge on accounting profits. The April 2026 clarifications confirm retroactive effect from 1 January 2024 and resolve several open questions on eligibility, duration, and the treatment of dividends.

Why the CFC test was a problem

Italian CFC rules attribute the income of a low-taxed foreign subsidiary directly to its Italian parent, even if no dividend is paid. The “low tax” threshold is set at 15% effective taxation, calculated as the ratio between the foreign company’s tax burden (current taxes, deferred taxes, and any portion of the qualified domestic minimum top-up tax under Pillar Two) and its accounting pre-tax profits. In practice, this calculation requires reconciling local GAAP financials, jurisdiction-specific tax adjustments, and Pillar Two figures every year — a heavy compliance exercise for groups with multiple foreign subsidiaries.

How the elective 15% regime works

Instead of running the full effective-tax-rate test, the Italian parent may elect to pay a substitute tax of 15% on the net accounting profit of the controlled foreign company, grossed up for current and deferred taxes, asset write-offs, and provisions. The election deems the standard CFC test satisfied, removing the need to attribute the foreign company’s income to the Italian parent.

The regime has three key design features confirmed by the new guidance. The election lasts three financial years, is irrevocable for the entire period, and renews automatically unless expressly revoked. It applies on an all-or-nothing basis: once chosen, it covers every CFC of the group whose passive income exceeds one-third of total revenue. The foreign company’s financial statements must be certified by locally authorised professional auditors, and those audited figures must feed into the Italian parent’s standalone or consolidating accounts.

If control is lost during the three-year period, or if the audit-certification requirement is no longer met, the option ceases — and where the audit failure affects one entity, the cessation extends to all CFCs of the group simultaneously.

Practical takeaways for foreign-owned and Italian groups

The retroactive application from 1 January 2024 is significant: groups can revisit financial years already filed and, where the 15% substitute tax produces a more favourable outcome, recover an unduly burdensome CFC inclusion through amended returns.

The choice between the elective 15% and the standard ETR test is rarely automatic. The flat regime tends to be advantageous where the foreign jurisdiction has timing differences that distort the standard ETR — large deferred tax movements, accelerated depreciation, asset write-offs — but where the underlying business is genuinely active. By contrast, where the foreign tax burden already comfortably exceeds 15% in cash terms, the standard test remains preferable because no Italian substitute tax is due at all.

Profit distributions from CFCs covered by the election receive coordinated treatment: the substitute tax paid at parent level is taken into account when dividends flow up, preventing the economic double taxation that would otherwise arise.

Final Considerations

The elective 15% regime is one of the most concrete simplifications introduced by Italy’s recent international tax reform, and the April 2026 guidance closes most of the operational gaps that had discouraged groups from opting in. For multinational groups with Italian holding structures — and for foreign-headed groups whose Italian parent or sister entity controls subsidiaries in lower-tax jurisdictions — the 2024 retroactive window is a real opportunity to reduce both compliance cost and tax exposure.

The interaction with Pillar Two, with double tax treaties, and with the CFC and anti-deferral rules of other jurisdictions is highly fact-specific. Anyone considering the election, or revisiting prior CFC inclusions, should run the numbers under both methods and obtain professional advice before filing.

Foreign Employers and Italy’s Permanent Establishment Risk: What Hiring an Italian Remote Worker Really Means

A foreign company that allows even a single employee to work from Italy on a regular basis can, under Italian rules, end up with a permanent establishment (PE) in the country — and with it, Italian corporate tax, VAT registration, payroll obligations, and a tax filing footprint it never planned for. After several years of post-pandemic remote-work normalisation, the Italian Revenue Agency has made clear that home-based work for a foreign employer is not a neutral arrangement: it is a fact pattern that must be analysed carefully before anyone signs a contract.

The legal framework starts with Article 162 of the Italian Income Tax Code (TUIR) and the OECD Model Tax Convention’s PE definition embedded in Italy’s treaties. A PE arises whenever a foreign enterprise has a fixed place of business in Italy through which its activity is carried on in whole or in part — or whenever a person habitually concludes contracts on its behalf in Italy (the so-called agency PE). Both routes are now actively scrutinised in remote-work scenarios.

When Does a Home Office Become a Fixed Place of Business?

Italian Tax Authority guidance — most notably Circular Letter 33/E of 2020 and Ruling 596/2021, repeatedly cited in subsequent practice — sets out the framework. A home office is not automatically a PE, but it can become one if four conditions converge: the worker carries out core revenue-generating activities (not just preparatory or auxiliary support); the employer effectively has the home at its disposal (for instance, by reimbursing rent, requiring its use, or providing office equipment that turns the space into a de-facto branch); the activity is sufficiently continuous; and there is no genuine alternative workplace abroad.

What this means in practice is that the substance of the role matters far more than its label. A back-office IT engineer running internal systems is unlikely to create a PE. A sales director negotiating contracts with Italian or European clients from her Milan apartment almost certainly does. The Italian Revenue Agency consistently applies a “substance over form” test during audits, and Italian tax courts have followed suit.

The Agency PE Trap

Even more dangerous than the fixed-place test is the agency PE route. A foreign company can be deemed to have a PE in Italy if a person — even one without formal signing power — habitually plays the principal role in the conclusion of contracts that are then routinely approved by the foreign head office without material change. Post-2017 OECD updates, transposed into Italy’s recent treaties, deliberately broadened this concept to capture commissionaire and similar arrangements. A remote sales manager living in Italy who manages the customer pipeline end-to-end is exposed even if all paperwork is signed abroad.

What an Italian PE Triggers

Once a PE is found, the consequences cascade. The foreign company must register a branch in Italy, allocate profits to it under transfer pricing principles, file Italian corporate tax (IRES at 24% plus IRAP at around 3.9%), register for Italian VAT and issue Italian e-invoices, and operate Italian payroll withholding for the local employee. Penalties for unregistered PEs are severe: undeclared income is subject to assessments going back up to seven years where no return was filed at all. Following the 2024 reform of the Italian penalty system (Legislative Decree 87/2024), the applicable penalties are now fixed rather than banded: 70% of the tax due for an understated return and 120% for an omitted return, replacing the former 90%–180% and 120%–240% ranges, which continue to apply only to violations committed before 1 September 2024. Criminal exposure remains once the omitted-tax threshold is crossed.

Practical Risk Mitigation

There is no single bullet-proof shield, but several measures materially reduce exposure: a written employment contract that confines the Italian role to internal or auxiliary functions; explicit prohibition on negotiating, finalising, or signing contracts with clients from Italy; absence of any “Italy office” designation on business cards, websites, or LinkedIn profiles; a clear alternative workplace abroad that the employee uses regularly; and avoidance of employer-paid rent or dedicated office equipment that could anchor a “fixed place” finding. For higher-risk roles, an Employer of Record (EOR) structure or a properly registered Italian branch is often the cleanest answer.

A Note for U.S. Citizens and U.S. Companies

The Italy–U.S. tax treaty contains its own PE article that broadly tracks the OECD model, but the U.S. dimension adds layers. A U.S. company with a hidden Italian PE has filing obligations on Form 8858 (for the Italian branch) and may face overlapping U.S. and Italian taxation that the foreign tax credit only partly resolves — particularly when state income tax is in play. For the U.S. citizen working remotely from Italy, the issue is reversed: even if the employer is shielded from PE because of careful role design, the individual still faces full Italian residence-based taxation on worldwide income, which is why the Impatriati regime, the new-resident lump-sum, or the 7% retiree regime are usually evaluated alongside the PE analysis.

Final Considerations

Italian PE risk is a quiet but expensive trap for foreign companies that adopt remote-work flexibility without legal review. The arrangement that looks costless to HR can produce a seven-year tax exposure for the parent. Before authorising an employee to work from Italy — even occasionally — foreign companies should obtain a written PE risk assessment, document the role boundaries, and revisit the analysis whenever the worker’s responsibilities expand. Specialist Italian tax advice is not optional in this area; it is the difference between a clean cross-border arrangement and a multi-year reconstruction.

Italy’s Flat Tax and Impatriati Regimes: The 2026 Window to Combine Both Closes from 2027

For several years, two of Italy’s most powerful inbound tax regimes — the non-dom flat tax for new residents and the new impatriati regime for inbound workers — could be applied together by the same taxpayer. That combination has produced striking outcomes for high earners: foreign passive income capped at a flat annual fee, and Italian-source employment or self-employment income taxed on only half of its amount. Decree-Law 38 of 27 March 2026 has now closed that door. From the 2027 tax year, anyone transferring tax residence to Italy must choose between the two regimes. Anyone who establishes Italian residence by 31 December 2026 keeps the combination intact for the full statutory duration of both regimes.

How the two regimes complement each other

The non-dom flat tax, governed by Article 24-bis of the Italian Income Tax Code, allows new residents to pay a fixed annual amount on all foreign-source income, regardless of size. The lump sum currently sits at €300,000 per year for the main applicant and €50,000 for each family member, for up to fifteen years. The regime targets high-net-worth individuals with significant offshore investments, dividends, capital gains, royalties, or rental income from abroad.

The new impatriati regime, introduced by Article 5 of Legislative Decree 209/2023, addresses a different tax base: Italian-source employment or self-employment income. Eligible inbound workers exclude 50% of that income from the IRPEF base for five years, with a 60% exemption available for parents who relocate with minor children. The annual income cap is €600,000.

Because the two regimes carve up the income map without overlap, combining them has been legitimate since the 2024 reform. The Italian Revenue Agency confirmed the cumulability in late-2025 guidance, treating the legislative silence on the point as an implicit green light. That silence is now over.

What the new rule actually says

DL 38/2026 introduces an explicit ban on cumulation, but only on a forward-looking basis. Taxpayers who establish Italian tax residence by 31 December 2026 continue to apply both regimes side by side for the full statutory duration of each. The protection is permanent and is not a phase-out. Taxpayers who transfer tax residence to Italy from 1 January 2027 onwards may elect either the flat tax or the impatriati regime, but not both. The election will be effectively binding for the duration of whichever regime is chosen.

The regime for professors and researchers is unaffected and remains separately combinable with other incentives.

What this means in practice

For anyone weighing an Italian move, the practical question is whether to bring it forward so the residence transfer takes effect before 2027. Italian tax residence is established when, for the majority of the tax year (more than 183 days), the individual maintains residence, domicile, or registered presence in Italy. For a 2026 move, this typically requires physical relocation by early July 2026 at the latest, supported by registration with the local anagrafe and consistent evidence that the personal and economic centre of life has shifted.

The combination is most valuable for taxpayers who have substantial foreign passive income — which the flat tax shelters at a flat €300,000 — and who will earn significant Italian-source professional or executive income, which the impatriati regime taxes on only half of its amount. For taxpayers whose profile is heavily weighted to only one of these two income streams, the choice imposed from 2027 will have a more limited financial impact, but the calculation should still be run carefully before any decision.

A Note for U.S. Citizens

U.S. citizens remain subject to worldwide taxation by the IRS regardless of where they reside. The flat tax can be treated as a creditable foreign tax in Italy, but its lump-sum nature complicates the per-country and per-basket allocation of the Foreign Tax Credit on Form 1116. Pairing it with the impatriati regime — under which half of Italian-source income is exempt from IRPEF — typically lowers the Italian tax actually paid on that portion, which in turn reduces the credit available against U.S. tax. In some scenarios this mechanically transfers part of the Italian saving into additional U.S. tax. A bilateral simulation, year by year and for the full intended duration of the regimes, is indispensable before relying on the combination as a planning strategy.

Final Considerations

The 2026 deadline is firm but the planning is not always simple. Establishing Italian tax residence, securing the flat tax election, and documenting eligibility under the impatriati regime are three distinct processes, each with its own timing and evidentiary requirements. For internationally mobile taxpayers considering Italy, this calendar year is the last opportunity to lock in the most generous version of the framework. Specialist advice that integrates both Italian and home-country tax positions is strongly recommended before any commitment is made.

The Italian Impatriati Regime in 2026: A Practical Overview for Workers Relocating to Italy

The Impatriati Regime is Italy’s main preferential tax incentive for qualified professionals who move their tax residence to the country. Restructured in 2024 and confirmed for 2026, it reduces the taxable base of Italian-source employment and self-employment income for a set number of years. Compared with the pre-2024 version, the current regime is more selective: lower exemption, shorter duration, stricter eligibility, and an income cap. ( FOR FULL DETAILS CLICK HERE )

Who Can Access the Regime

To qualify in 2026, an individual must simultaneously meet five conditions. The first is the transfer of tax residence to Italy under Italian domestic rules. The second is not having been an Italian tax resident in the three tax years preceding the transfer; this look-back period is extended to six years, or seven in some cases, if the worker continues to work in Italy for the same employer or the same group they worked for abroad.

The third condition is a commitment to remain an Italian tax resident for at least four years: losing residence earlier triggers recapture of the benefit with interest. The fourth is that work must be performed mainly in Italy — more than 183 days in the tax year. The fifth, and most restrictive, is the high qualification or specialization requirement: the worker must hold a qualification recognised under EU rules on regulated professions or on highly qualified employment (the EU Blue Card framework), or have equivalent specialised competences. Generic or low-skill roles are excluded.

Eligible Income

The regime applies to Italian-source employment income and self-employment income from arts and professions, including directors’ fees for duties performed in Italy. Business income from sole traders and partnerships, as well as passive income such as dividends, interest, capital gains and rental income, is not eligible and is taxed under the ordinary rules.

Benefits and Duration

The standard benefit is a 50 percent exemption of eligible income from IRPEF: only half is subject to Italian progressive income tax, and the same reduced base also applies to regional and municipal surtaxes. The exemption increases to 60 percent if the worker has a minor dependent child at the time of transfer or becomes a parent during the benefit period, provided the child resides in Italy.

The regime is capped at 600,000 euro of eligible income per year; any excess is fully taxed at ordinary rates. The duration is five tax years, starting from the year of transfer. Unlike the previous version, no extensions are available, not even where children or real estate purchases previously triggered a five-year extension.

Practical Points Before the Move

Eligibility turns on documentation. Returning Italian nationals must formally cancel their AIRE registration; foreign nationals must complete anagraphic registration with the Italian municipality. A codice fiscale is required, as is evidence of foreign residence during the look-back period — foreign tax returns, contracts, utility bills, AIRE certificates. Employees then submit a written request to the Italian employer, who applies the reduced withholding on monthly payroll; self-employed professionals apply the reduction directly in the annual tax return.

Common pitfalls include missing the 183-day test because of frequent remote working abroad, miscalculating the extended six- or seven-year look-back for those staying with the same group, and failing to document the high qualification requirement, which the Italian Revenue Agency is increasingly auditing. The regime is not combinable with the forfettario flat-tax regime, the 7 percent retiree regime for Southern Italy, or the lump-sum flat tax for new residents.

A Note for U.S. Citizens

U.S. citizens and green card holders continue to be taxed by the United States on worldwide income regardless of residence, and must keep filing Form 1040, FBAR and, where applicable, Form 8938. Because the Italian exemption reduces the Italian tax paid, the Foreign Tax Credit available to offset U.S. liability is lower, and residual U.S. tax may actually increase. The Italy–U.S. treaty’s saving clause preserves U.S. taxing rights over its citizens, so treaty relief is limited. Italian mutual funds and certain insurance wrappers are typically classified as PFICs and trigger punitive U.S. taxation and heavy reporting, and Italian complementary pensions may not qualify as tax-favoured plans under U.S. rules. A coordinated U.S./Italy projection before relocating is essential to model FTC, FEIE, state tax exit, and investment restructuring options.

Final Considerations

The 2026 Impatriati Regime remains a powerful incentive, but it rewards careful planning. Residence timing, documentation, the high qualification test and the interaction with other regimes can materially change the net benefit — and for U.S. persons the analysis must always be run on both sides of the Atlantic. Professional advice before the move is strongly recommended.

Italy’s 2026 Short-Term Rental Reform: Three-Property Threshold, CIN Enforcement, and EU Platform Reporting

Italy has restructured the tax and regulatory framework for short-term rentals from 1 January 2026, with a second wave of changes arriving in May 2026 under EU Regulation 2024/1028. The combined effect is a tighter environment for anyone letting a property for stays under 30 days — and a particularly important moment for international owners who rely on platforms such as Airbnb, Booking.com and Vrbo to reach guests.

The three-property threshold

The 2026 Budget Law has lowered the threshold at which short-term rental activity is classified as a business from five properties to three. Owning or managing three or more properties used exclusively for lettings of less than 30 days now triggers mandatory VAT registration, opening of a Partita IVA, social security contributions to INPS, and full business accounting.

This is a significant change. Small foreign investors who built a portfolio of three or four Italian apartments for vacation rental — a very common profile among international buyers — are automatically reclassified as businesses from this year, even if they previously enjoyed the straightforward cedolare secca treatment.

Cedolare secca: what stays and what changes

For non-professional hosts (one or two properties), cedolare secca remains available. The rate is 21% on the first property and 26% on each additional property, applied on gross rental income in lieu of IRPEF and local surtaxes. A proposal during the 2026 Budget Law debate to raise the first-property rate to 26% was dropped, so the pre-2026 structure has survived for the smallest landlords.

Owners above three properties lose access to cedolare secca entirely. Rental income falls into ordinary business taxation, subject to IRPEF on progressive brackets, IRAP in certain cases, and VAT where the activity takes on a hotel-like character (breakfast, cleaning between guests, reception desk).

CIN and the end of anonymous listings

Every property offered for short-term tourist use must now display a CIN (Codice Identificativo Nazionale) issued by the national accommodation database. Platforms are required to verify CIN compliance and delist properties without one. Fines for CIN violations range from €800 to €8,000 per property. Over 620,000 CINs were issued in the first year of operation — an indicator of just how actively the authorities are enforcing the new regime.

May 2026: EU platform reporting kicks in

From 20 May 2026, EU Regulation 2024/1028 requires platforms to transmit booking data directly to national authorities on a monthly basis. Owner identity, property address, number of nights booked, and amounts received will all flow automatically to the tax authorities. Foreign owners who, under previous opacity, were informally relying on platform payouts to a foreign bank account should assume that this data is now visible to the Agenzia delle Entrate in real time — and that any mismatch between declared income and reported bookings will be pursued.

Practical points for international owners

Anyone holding two properties and considering a third should run the numbers carefully — the tax, accounting and social-security burden of crossing the business threshold can easily outweigh the marginal return on a single extra unit. A different corporate structure (such as an Italian SRL) may work better at scale, but brings its own regime and compliance costs. For owners already at or above three properties, the priority is proper VAT registration and bookkeeping from day one of 2026 — corrective filings later in the year are possible but expensive.

A Note for U.S. Citizens

U.S. citizens remain taxable on worldwide rental income regardless of Italian residency status. Italian tax paid under cedolare secca or IRPEF is generally creditable in the United States via the Foreign Tax Credit, but cedolare secca’s flat structure sometimes produces mismatches with U.S. Schedule E mechanics, where expenses are normally deductible against gross rent. Properties held through Italian companies, or bank accounts used to receive rental payouts, can also trigger FBAR, FATCA, and in some cases PFIC reporting. These layers should be planned together before any scaling of Italian rental activity.

Final Considerations

The 2026 reform does not make short-term rental unattractive in Italy, but it ends the informal era. Owners who cross the three-property threshold, owners approaching it, and owners of even a single property without a CIN all face concrete compliance steps this year. Professional advice is strongly recommended before restructuring or expanding a portfolio.

Impatriati Regime and Minor Children: Why Families Moving to Italy Can Now Access the 60% Exemption More Easily

A recent clarification from the Italian Revenue Agency has expanded how the impatriati regime interacts with one of its most attractive features: the enhanced exemption for taxpayers with minor children. Response No. 82 of March 20, 2026 addressed a practical question that had been troubling international families and their advisors — whether the enhanced benefit applies when the children are already tax resident in Italy before the parent actually returns. The answer is yes, with significant consequences for planning a family relocation.

The current inbound workers regime, set out in Legislative Decree 209/2023, reduces the taxable base on Italian-source employment and self-employment income. The standard benefit cuts the taxable portion to 50% of income produced in Italy, applied for five tax years and capped at a maximum eligible income of €600,000 per year. For a worker returning under qualifying conditions, this halves the IRPEF burden on Italian earnings for half a decade, which is why the regime has become central to relocation planning for international professionals.

The Enhanced Benefit for Families

Where the taxpayer has at least one minor child who is tax resident in Italy, the taxable base falls further, from 50% to 40%. In practical terms, this means 60% of Italian-source income is exempt from IRPEF instead of 50%. The enhanced benefit is also triggered by the birth or adoption of a child during the five-year incentive window — in which case the improved treatment applies from the tax period in which the event occurs and continues for the remaining eligible years.

The benefit requires the child to be tax resident in Italy, and that residence must be maintained throughout the benefit period. If the child later leaves Italy, the enhanced treatment ceases from the year in which that condition is no longer satisfied.

t requires the child to be tax resident in Italy, and that residence must be maintained throughout the benefit period. If the child later leaves Italy, the enhanced treatment ceases from the year in which that condition is no longer satisfied.

What the March 2026 Clarification Adds

The key point in Response No. 82/2026 is the timing of the child’s residence. The Revenue Agency confirmed that it is not necessary for the child’s transfer to Italy to coincide with, or follow, the parent’s relocation. A minor child who was already resident in Italy before the incoming worker actually qualifies as a resident triggers the enhanced benefit, provided Italian residence is preserved for the duration of the regime.

This matters in real-life patterns the firm sees often: a parent who spent recent years working abroad while the family remained in Italy; a couple where one spouse relocated ahead of the other with the children; or international families who sent children to Italian schools before committing to a full household move. Under the previous reading, some practitioners were cautious about claiming the enhanced 60% exemption in these scenarios. The 2026 clarification removes that uncertainty.

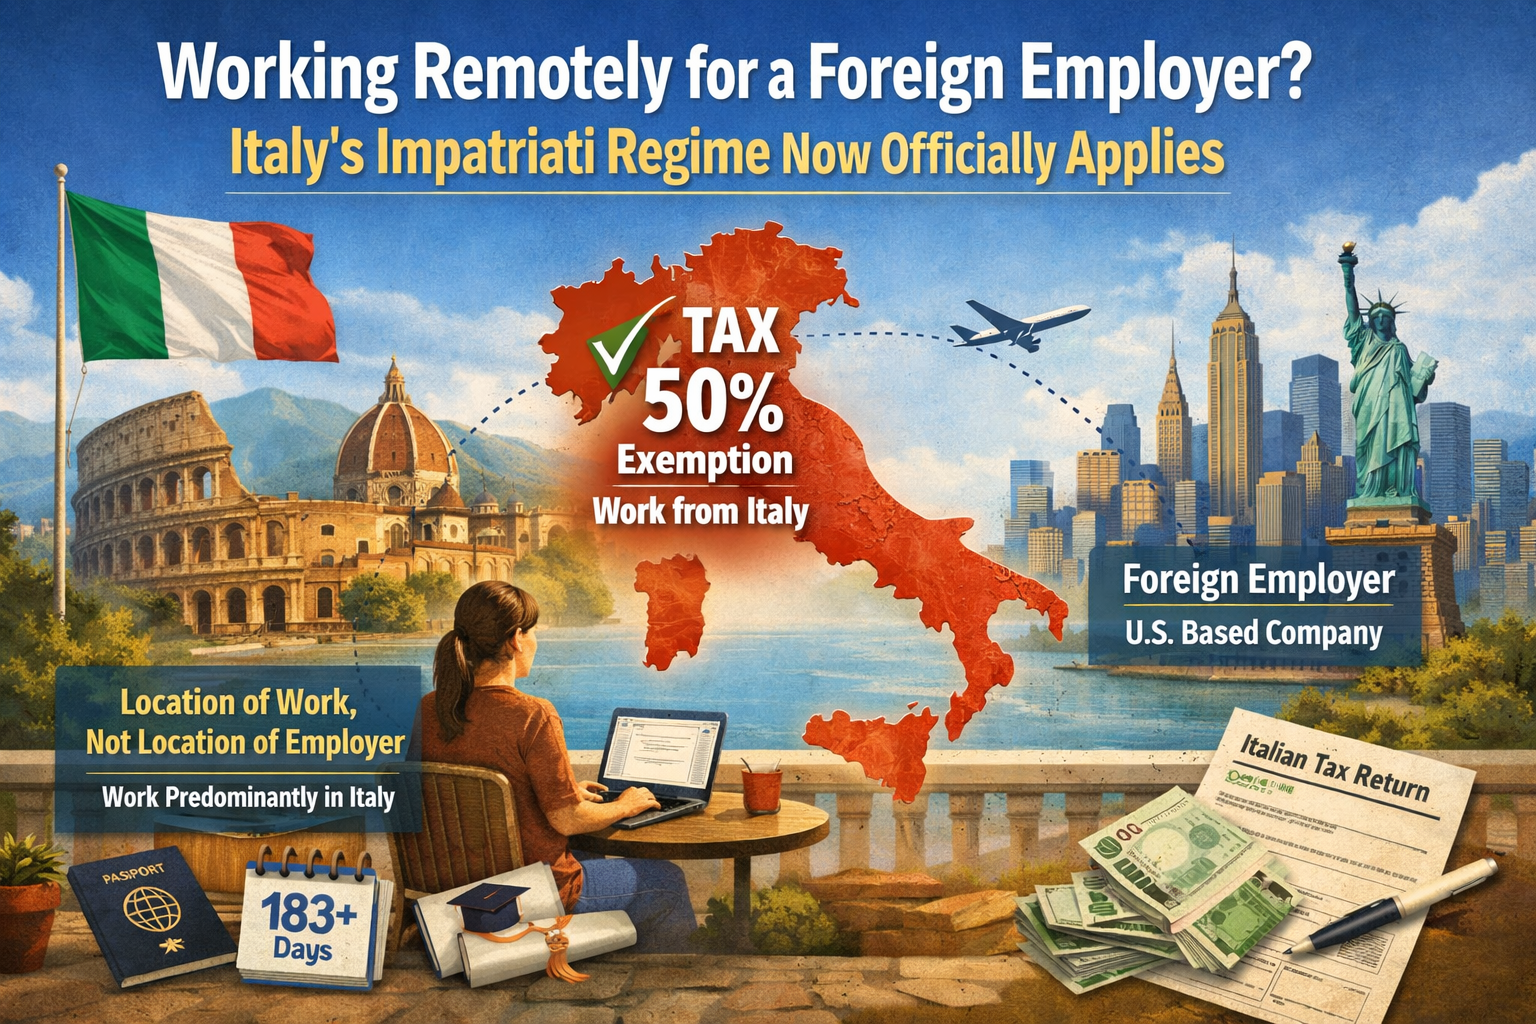
The same ruling reaffirms a second important point: the regime is compatible with smart working for a foreign employer. A worker who returns to Italy while continuing the same employment relationship with a non-Italian company may still qualify, provided the activity is performed predominantly from Italian territory and the other statutory conditions — including the foreign residence requirement prior to transfer — are satisfied.

A Note for U.S. Citizens

Because the United States taxes its citizens on worldwide income regardless of residence, a U.S. citizen benefiting from the Italian impatriati regime still files a U.S. return. The enhanced 60% Italian exemption means a smaller amount of Italian tax is paid on the same gross Italian income, which in turn reduces the Foreign Tax Credit available on the U.S. return. The practical result is that the Italian saving can translate into a higher residual U.S. liability rather than a straightforward net reduction in total tax. FBAR and FATCA obligations remain unchanged. A coordinated U.S.–Italy projection is essential before assuming the headline benefit will flow through to cash savings.

Final Considerations

The impatriati regime is one of the most powerful tools Italy offers to international workers, and the enhanced rate for families makes it particularly relevant to households planning a long-term move. The March 2026 clarification opens the door to a broader set of scenarios, but the rules on tax residence, timing of the transfer, and the child’s continued Italian residence leave no room for improvisation. Anyone considering a move — or already inside the five-year window — should have the family’s situation reviewed before filing decisions are locked in.

Selling Into Italy From Abroad: The July 2026 Customs Shake-Up for Low-Value Parcels

On 1 July 2026 two separate but overlapping reforms will change the cost structure of shipping low-value goods into Italy from outside the European Union. The EU will introduce a flat €3 customs duty on every item in parcels valued up to €150 sent to consumers, and Italy will simultaneously raise its own handling fee from €2 to €3 per parcel to align with the EU measure. For any foreign company that relies on direct-to-consumer shipping into the Italian market — US, UK, Swiss or Asian sellers especially — the break-even maths changes materially, and the window to restructure is short.

The Italian fee has actually been in place since 1 January 2026. It applies to non-EU low-value consignments cleared through Italian customs, regardless of the declared value of the goods. It is charged per parcel, not per item, and is collected by the customs clearance agent from the importer of record — in most B2C cross-border sales, that is the end consumer. The increase to €3 scheduled for 1 July 2026 is not a new fee but an adjustment of the existing charge so that the Italian administrative cost matches the new EU duty.

The EU-level reform is more disruptive. The flat €3 customs duty is an interim measure, introduced ahead of the full abolition of the €150 de minimis exemption expected in 2028. Unlike the Italian handling charge, the €3 duty is assessed per item and is based on the tariff classification of the goods. A single parcel containing three distinct SKUs with different tariff headings will therefore attract €9 in customs duty, before VAT and before Italy’s €3 handling fee.

Who absorbs the cost

In a standard non-EU B2C shipment using IOSS (Import One Stop Shop), VAT is pre-collected at the point of sale by the seller. IOSS continues to work under the new rules for the VAT piece, but the customs duty and the handling fee are in addition. Sellers outside the EU have three practical choices. They can pass the combined cost (up to €6 per parcel, plus duty-per-item) on to the Italian consumer at checkout, which is transparent but damages price competitiveness. They can absorb it into the sale price, which compresses margins. Or they can restructure the supply chain — holding stock inside the EU, shipping business-to-business into an EU warehouse, and fulfilling the Italian consumer from within the single market, which removes the import event entirely.

Routing alternatives are narrower than they appear

Because Italy’s handling fee is triggered only when goods are physically cleared at an Italian customs office, it is possible in theory to route shipments through another EU entry point (for example Germany or the Netherlands) and transit them to Italy under intra-EU movement rules. In practice, other Member States are introducing their own handling charges aligned to the EU reform, so the arbitrage window is closing. Foreign sellers should model the total landed cost country by country rather than assuming a single optimised route.

A Note for U.S. Citizens

For U.S.-based sellers shipping directly to Italian consumers, the practical impact is immediate: the Section 321 de minimis logic that allows low-value shipments into the U.S. duty-free has no EU analogue from July 2026. Any seller currently operating on the assumption that parcels under €150 reach Italy duty-free should update their checkout flow and customer communications before the July deadline. U.S. sellers should also verify that their IOSS intermediary is ready to collect the flat €3 duty alongside VAT; if not, duty becomes payable on arrival and parcels may be held pending payment.

Final Considerations

The July 2026 reforms are not about revenue — the EU is aligning its treatment of low-value imports with the reality that the €150 threshold has become a compliance loophole. For foreign sellers the strategic question is no longer “how do I minimise per-parcel friction?” but “where should my European stock actually sit?” Sellers with meaningful Italian volume should evaluate a warehouse inside the EU, IOSS readiness, and tariff-classification discipline well before the deadline. Each of these choices has VAT, customs, and permanent-establishment implications that need to be modelled together, not in isolation.

Foreign companies selling into Italy are encouraged to review their customs and VAT position with qualified advisers before the July 2026 changes take effect.

Italy’s Avviso Bonario: What It Is and What to Do When You Receive One

An avviso bonario is a preliminary notice issued by the Italian Revenue Agency (Agenzia delle Entrate) when automated or formal checks of a tax return reveal possible irregularities. It is not yet a formal assessment and not yet a tax bill — it is an invitation to either pay what the Agency believes is due, or demonstrate why the Agency is wrong, at substantially reduced penalties. For foreign residents and international businesses operating in Italy, handling it correctly is essential: ignoring the notice almost always leads to enforcement action at a much higher cost.

When and How It Arrives

The avviso bonario is generated after one of two types of control performed on a return already filed:

The automated check (controllo automatizzato), under Article 36-bis of Presidential Decree 600/1973 for direct taxes and Article 54-bis of Presidential Decree 633/1972 for VAT, is a computerised matching between what was declared and what was actually paid or withheld.

The formal check (controllo formale), under Article 36-ter, is a deeper review where the Agency verifies supporting documentation for deductions, tax credits, withholdings and other specific items on the return.

The notice usually arrives two to three years after the return was filed. For taxpayers who filed independently, it is delivered by registered post or made available in the taxpayer’s online tax account (cassetto fiscale). For those who filed through an accountant or a CAF, the notice is transmitted electronically via the Entratel channel directly to the intermediary, who is expected to forward it promptly.

Which Taxes and Contributions Are Covered

Avvisi bonari can concern virtually every tax or contribution managed through the Italian tax return: IRPEF and IRES (personal and corporate income tax), IRAP, VAT, cedolare secca on rental income, IVIE and IVAFE on foreign real estate and financial assets, regional and municipal surcharges, substitute taxes on investment income, and withholding taxes. They also cover INPS social security contributions reported through the tax return, which is particularly relevant for self-employed professionals and holders of a partita IVA.

Payment Terms and Reduced Penalties

The key advantage of resolving an avviso bonario is a significant reduction of the statutory penalty.

For automated checks, the penalty is reduced to one-third of the ordinary amount. For formal checks, the reduction is to two-thirds. Following the 2024 reform of the Italian penalty system, the base penalty for omitted or insufficient payment is 25 percent for violations committed from 1 September 2024 onwards (it was 30 percent before that date). In practice, the effective penalty after reduction is approximately 8.3 percent for automated controls and 16.7 percent for formal ones, plus interest accrued from the original deadline to the date of payment.

To benefit from the reduction, the taxpayer must pay within 30 days from receipt of the notice. When the notice is routed through a tax intermediary, the effective deadline is 90 days from the Agency’s transmission date.

Since January 2025, installment plans have been standardised: up to 20 quarterly installments are now available regardless of the amount due. Missing the first installment — or any two later ones in a row — causes the entire balance to become immediately payable with full penalties.

What to Do If You Receive One

The first step is to check whether the figures are correct. Common triggers include F24 payments not properly matched to the return, missing or misreported withholdings, documentation not transmitted by third parties (for example, medical expenses or mortgage interest), and double-counting of tax credits.

If the notice is correct, payment is made with the pre-filled F24 form attached to the communication, or through an installment request submitted via the taxpayer’s online account.

If the notice contains errors, the taxpayer or their advisor can file a CIVIS request — an online service dedicated to the review of avvisi bonari — attaching documentation that supports the original return. The 30-day payment deadline is not automatically suspended, so the request should be filed immediately. In the majority of cases, a well-documented CIVIS submission leads to full or partial cancellation of the notice.

Ignoring the avviso bonario is the worst possible option. After the deadline, the sum is referred to Agenzia delle Entrate Riscossione, and a formal cartella di pagamento is issued with full penalties, statutory interest and collection fees. At that point, the reduced-penalty benefit is permanently lost, and recovery may include wage or bank account attachments.

A Note for U.S. Citizens and Other Foreign Taxpayers

Expats frequently receive avvisi bonari because of mismatches in the reporting of foreign income, foreign tax credits, or assets held abroad (quadro RW). Before paying, it is always worth checking whether the underlying issue is a genuine additional liability or a reporting mismatch that can be corrected. In many cross-border situations, the notice can be cancelled by producing evidence of foreign withholding tax actually paid or of treaty-based relief. U.S. citizens should be especially careful: an Italian adjustment can change the Foreign Tax Credit position on Form 1116, and any correction on the Italian side may require a corresponding amendment in the U.S. return to preserve the credit.

Final Considerations

An avviso bonario is not yet a legal dispute — it is the final opportunity to resolve a tax position at a reduced cost and without litigation. The 30-day window is short, but it is almost always enough either to pay, to request installments, or to challenge the figures through CIVIS. Given the cross-border complexity that typically affects expats and foreign companies in Italy, the most effective course of action is to involve a qualified Italian tax professional as soon as the notice is received — well before the deadline, rather than after.

U.S. Trusts and Italian Tax Residency: The 2026 Ruling That Redefines Interposition for Inbound Beneficiaries

U.S. Trusts and Italian Tax Residency: The 2026 Ruling That Redefines Interposition for Inbound Beneficiaries

A recent ruling by the Italian Revenue Agency — Response to Ruling Request No. 81 of 18 March 2026 — sets a sharper standard for how foreign trusts are treated once a beneficiary becomes tax resident in Italy. The decision concerns a Delaware irrevocable trust, classified as a “complex trust” and fiscally autonomous in the United States, whose principal beneficiary was preparing to move to Italy. The Agency concluded that the trust was fiscally interposed — meaning it does not exist as a separate taxpayer for Italian purposes — and that all of its income and assets must be reported directly by the beneficiary. The ruling is an important signal for any international family considering relocation to Italy with an existing U.S. trust structure.

The case in brief

The trust was established in 2024 under Delaware law. It held U.S. financial assets and an interest in a New York LLC owning real estate. The settlor had retained a testamentary power to designate, via will or fiduciary instrument, the ultimate recipients of the trust capital. The beneficiary, still non-resident at the time of the request, asked the Revenue Agency to confirm that — once she moved to Italy — the trust would be treated as a non-interposed entity, i.e. as a separate taxable layer between her and the underlying assets.

The Agency disagreed. Even though the trust was irrevocable, discretionary, and administered by an independent trustee, the residual powers retained around the final destination of the capital were enough, in the Agency’s view, to displace the trust’s fiscal autonomy.

Why the trust was recharacterised

The ruling confirms a principle that has been consolidating in Italian tax practice: a trust earns independent fiscal relevance only when real divestment of control has occurred — not merely when the paperwork says so. The Agency looks through the structure and tests whether any party (settlor or beneficiary) still holds meaningful influence over how the assets are managed or distributed.

Three elements proved decisive. First, the testamentary designation clause, which allowed the settlor to reshape the final destination of the trust capital. Second, the possibility that the beneficiary could indirectly influence distributions through will or fiduciary arrangements. Third, the conditioned discretion of the trustee, whose autonomy was not absolute in practice.

The ruling is significant because it extends the concept of interposition to formally correct, properly drafted structures. A trust that looks irrevocable and discretionary on paper can still be disregarded for Italian tax purposes if influence over the assets survives, even in latent or testamentary form.

What this means for an inbound beneficiary

If the Italian Revenue Agency recharacterises a foreign trust as interposed, the fiscal consequences fall squarely on the Italian-resident beneficiary. The trust effectively disappears as a taxable subject, and the beneficiary must report all trust income — interest, dividends, capital gains, rental income — in the Italian personal tax return, as if the assets were held directly; disclose the underlying foreign assets through the Quadro RW monitoring framework; and pay IVIE on the foreign real estate and IVAFE on the foreign financial assets held in the trust.

This treatment applies from the first year of Italian tax residency.

A Note for U.S. Citizens

U.S. citizens face a particularly delicate overlap. Under U.S. rules, a Delaware complex trust is typically a separate taxpayer filing Form 1041, while a grantor trust is transparent to the settlor. Italy, by contrast, may ignore both classifications and look straight through to the beneficiary. The result can be a mismatch in who is taxed on what, and when — creating friction in the Foreign Tax Credit mechanism and potentially leaving trust income unrelieved under the Italy–U.S. treaty. FBAR and FATCA obligations continue regardless of how Italy classifies the trust, and the beneficiary may end up with parallel — and partly inconsistent — reporting duties on both sides of the Atlantic. Structures set up before relocation should be stress-tested well in advance.

Practical points before moving to Italy

Anyone planning a move to Italy with an existing foreign trust should review the deed for any retained powers — including testamentary designation, letters of wishes with binding effect, or informal influence over the trustee. Removing or properly insulating these elements prior to the transfer of residence is often the difference between fiscal opacity (trust taxed as a separate entity) and full pass-through to the beneficiary.

Final Considerations

Ruling 81/2026 does not change the law, but it narrows — clearly and publicly — the space in which a foreign trust can claim fiscal autonomy once its beneficiary becomes Italian-resident. For U.S. families in particular, the interaction between Italian interposition doctrine and U.S. trust classification deserves careful, personalised review before the move. Specialist advice is strongly recommended, ideally at least twelve months ahead of the change in tax residency, to allow structural adjustments where needed.

Italy’s 2026 PEX Reform: New Thresholds for Capital Gains on Minority Stakes in Italian Companies

Italy’s 2026 PEX Reform: New Thresholds for Capital Gains on Minority Stakes in Italian Companies

Italy’s 2026 Budget Law (Law 199/2025) has reshaped the way capital gains on shareholdings are taxed at the corporate level. Starting 1 January 2026, the Participation Exemption (PEX) — the long-standing regime that exempts 95% of qualifying capital gains from corporate taxation — applies only when new size thresholds are met. For holding companies, entrepreneurs, and cross-border investors, this is not a technical footnote: it is a structural change that affects deal economics, exit strategies, and how minority investments are held.

What the PEX Regime Does

Under Article 87 of the Italian Income Tax Code (TUIR), capital gains realised by an IRES taxpayer on the sale of a qualifying shareholding are 95% exempt, meaning only 5% of the gain is subject to Italy’s 24% corporate income tax — an effective rate of just 1.2%. The same regime applies by extension to EU and EEA companies selling Italian participations, provided they have no permanent establishment in Italy. Until the end of 2025, the core PEX requirements were qualitative: the subsidiary had to be a genuine operating business, resident in a non-blacklisted jurisdiction, with the shareholding held for at least 12 months and classified as a financial fixed asset.

What Changed in 2026

The 2026 Budget Law keeps the qualitative conditions but adds a quantitative gate. From 2026 onward, the 95% exemption on capital gains is available only if the shareholding disposed of meets at least one of the following:

A direct or indirect participation of at least 5% of the share capital or voting rights, or

A shareholding with a tax value of at least €500,000.

If neither threshold is satisfied, the capital gain is fully taxable at the ordinary 24% IRES rate — a dramatic jump from the 1.2% effective rate most groups are used to. The same thresholds mirror those now applicable to intercompany dividends under Law 199/2025, creating a unified regime for both distributions and exits.

Who Is Most Affected

The reform hits minority investments hardest. The clearest losers are holding companies and corporate investors whose stake in an Italian target sits below 5% and whose tax basis is under €500,000. This is a common profile in several situations: founders whose shareholding has been diluted across successive funding rounds; early-stage investors in startups that have since raised significant capital; family holding structures with small strategic positions; and corporate venture arms holding observer-sized stakes. On exit, these investors now face a full 24% corporate tax on the gain instead of the familiar 1.2% effective rate.

Club Deals and Joint Investments

Club deals — where several investors pool capital into a single special-purpose vehicle to acquire a target — are particularly exposed. If the pooled SPV holds 5% or more of the target, PEX applies at the SPV level; the problem arises when individual investors in the SPV hold below-threshold indirect positions through their own corporate vehicles. The Italian Parliament has signalled, through Chamber Act 2750/2025, that legitimate club-deal structures should not be treated as abusive. Detailed implementing guidance is still awaited, and investors structuring club deals in 2026 should document the business rationale of each layer carefully.

A Note for U.S.

U.S. citizens and U.S.-based investors holding Italian participations through corporate vehicles need to reassess the after-tax economics of their Italian positions. A gain that was once taxed at 1.2% in Italy and credited against U.S. federal tax under the Foreign Tax Credit rules is now potentially taxed at 24% in Italy. Depending on the structure, this may generate excess foreign tax credits, shift the residual U.S. liability, or trigger review under anti-hybrid and PFIC rules where investments sit inside non-U.S. holding companies. The Italy–U.S. tax treaty does not override these domestic Italian thresholds. Any restructuring should be modelled jointly by Italian and U.S. advisors before the next disposal event.

Final Considerations

For groups that hold Italian investments strategically through corporate entities, the 2026 PEX reform is a reason to revisit the tax basis and percentage of every participation on the books. Where minority stakes fall below both thresholds, options include consolidating holdings, stepping up the tax basis through elective revaluations when available, or timing disposals in light of the new rules. As always with Italian tax reform, the qualitative conditions of PEX still matter and must be verified alongside the new quantitative gate. Professional advice is essential before any disposal, reorganisation, or cross-border restructuring affecting Italian participations.

Italy’s Digital Nomad Visa: What Remote Workers Need to Know About Tax and Social Security

Italy formally launched its Digital Nomad Visa under Legislative Decree 4/2022, and in early March 2026 the government published long-awaited implementing guidelines that clarify who qualifies, what documentation is required, and — crucially — how Italian tax and social security rules apply. If you are working remotely for a client or employer based outside Italy and considering a move, understanding the tax framework is at least as important as securing the visa itself.

Who the Visa Is For

The framework distinguishes between two categories of applicant. Self-employed digital nomads are freelancers or sole traders who provide services to clients outside Italy. Remote workers are employees of a foreign company who carry out their duties entirely from Italy. Both categories require an initial residence permit valid for up to one year, renewable, but the documentation and compliance obligations differ.

To qualify, applicants must demonstrate a minimum annual income of approximately €28,000 — some consulates apply a stricter threshold in practice — along with private health insurance covering at least €30,000, a confirmed rental contract or property deed, and evidence of at least six months of relevant professional experience. Family members (spouse and dependent children) receive co-terminous residence permits and gain access to Italy’s national health service once the principal permit is issued.

How Italian Tax Works for Digital Nomads

Contrary to what some online guides suggest, Italy does not have a dedicated tax regime for digital nomad visa holders. Ordinary Italian tax rules apply from the moment you become an Italian tax resident — which occurs once you spend more than 183 days in Italy in a calendar year, register at the municipal registry office, or establish your habitual abode in Italy.

For self-employed digital nomads, the most immediately useful structure is the flat-rate regime (regime forfettario). Eligible freelancers pay a substitutive tax of 5% on a deemed percentage of gross revenues for the first five years, rising to 15% thereafter, provided annual income does not exceed €85,000. Compliance is significantly simplified, as there is no VAT to charge clients abroad and accounting requirements are minimal.

Employees or those who do not qualify for the flat-rate regime are subject to ordinary progressive income tax (IRPEF) at rates up to 43%. Some remote workers who relocate to Italy may separately qualify for the inbound workers regime (regime impatriati), which exempts 50% of qualifying employment or professional income from IRPEF for five years. However, this regime has its own eligibility conditions — including prior foreign residence of at least two of the previous three years, a commitment to remain in Italy for at least four years, and a qualification or specialisation requirement — and it must be applied for separately. Holding the digital nomad visa does not automatically confer access to it.

Social Security: A Frequently Overlooked Obligation

Self-employed visa holders must register with INPS and pay contributions to the Gestione Separata (separate social security fund) at a rate of approximately 26% on net taxable income. This adds substantially to the cost of working in Italy as a freelancer and is often underestimated at the planning stage.

For employees of foreign companies, the applicable social security framework depends on whether Italy has a totalization agreement with the employer’s home country. Where such an agreement exists — as it does with the United States — contributions may remain payable in the home country rather than in Italy for a defined period.

The Permanent Establishment Risk for Employers

One of the most significant tax risks of the digital nomad framework does not fall on the individual at all: it falls on the foreign employer. When an employee works from Italy continuously and at the employer’s direction, Italian tax authorities may classify the worker’s home office as a fixed place of business — creating a permanent establishment of the foreign company in Italy and exposing the employer’s profits to Italian corporate tax. This risk is particularly acute for employees who set up Italian tax residency on a long-term basis. Foreign employers with staff relocating under the digital nomad visa should assess their permanent establishment exposure before approving the arrangement.

A Note for U.S. Citizens

U.S. citizens are taxed by the United States on their worldwide income regardless of where they live, so moving to Italy does not eliminate the U.S. filing obligation. Italy and the United States have a double tax treaty, and Italian taxes paid on income also subject to U.S. tax are generally creditable against U.S. federal tax via the Foreign Tax Credit (Form 1116). However, the flat-rate regime (forfettario) presents a complication: because it operates as a substitutive tax rather than a standard income tax, the IRS may not treat it as a creditable foreign income tax, meaning forfettario users could face both Italian and U.S. tax on the same income without full offset. This point deserves specific analysis before choosing the forfettario option. FBAR and FATCA reporting obligations for Italian financial accounts also continue to apply regardless of which Italian tax regime is chosen.

Final Considerations

Italy’s Digital Nomad Visa gives remote workers a clear legal pathway to live and work in Italy that did not exist before. The tax picture is more complex than the visa rules alone suggest: choosing the right Italian tax structure, understanding the social security obligations, assessing the permanent establishment risk to your employer, and managing any home-country obligations simultaneously all require careful planning. The interaction between the digital nomad visa and Italy’s various incentive regimes is an evolving area, and proposed changes to the Budget Law could alter the landscape further in the near term. Professional advice tailored to your specific situation — covering both Italian and home-country tax — is essential before making the move.

Non-EU Companies in Italy: The €50,000 VIES Guarantee Is Mandatory and Here to Stay

Non-EU Companies in Italy: The €50,000 VIES Guarantee Is Mandatory and Here to Stay

Since April 2025, any company incorporated outside the European Union or the European Economic Area that conducts intra-Community VAT transactions through Italy has been required to provide a financial guarantee of at least €50,000. The obligation was introduced by a Ministerial Decree of 4 December 2024 and became operational with the Revenue Agency implementing measure of 14 April 2025, which set the procedure and started the 60-day clock for businesses already registered. It survived its first serious legal challenge in early 2026. Foreign companies that have been waiting for a court-ordered reprieve should no longer count on one.
What Is VIES and Why It Matters
The VAT Information Exchange System (VIES) is the EU-wide database that identifies entities entitled to apply zero VAT on cross-border sales and purchases between registered businesses. Active VIES listing is essential for any company involved in intra-Community supply chains: without it, every cross-border sale to an EU buyer is subject to full Italian VAT, and the ability to purchase goods zero-rated from EU suppliers disappears. For companies that rely on European trade flows, exclusion from VIES is a serious operational disruption.
Who Must Provide the Guarantee
The obligation falls exclusively on non-EU and non-EEA companies that operate through an appointed fiscal representative in Italy. This is the key distinction. EU-based companies can register for Italian VAT directly and are exempt from the guarantee. Companies based in the United States, the United Kingdom (post-Brexit), Canada, Switzerland, and other non-EEA countries cannot use direct VAT registration and are legally required to appoint a fiscal representative — a locally based individual or entity jointly and severally liable for their Italian VAT obligations. It is this class of companies that must now post the guarantee.
What the Guarantee Requires
Three forms of security are accepted under the MEF Decree of December 4, 2024: a deposit in Italian government bonds or state-backed securities, an insurance surety bond, or a bank guarantee issued under Law No. 348/1982. The minimum amount is fixed at €50,000, with no possibility of reduction based on company size or transaction volume. The guarantee must be issued in favour of the director of the Revenue Agency’s Provincial Office at the fiscal representative’s tax domicile and must remain valid for a minimum of 36 months. For new registrations, the guarantee must be in place from day one. Companies already listed in VIES when the obligation was introduced had until June 13, 2025 to comply; those that failed to do so face automatic exclusion from the VIES database.
The Court Challenge and Its Outcome
A coalition of approximately 20 non-EU businesses — primarily Chinese e-commerce traders supported by two trade associations — filed an appeal with the Regional Administrative Court of Lazio (TAR Lazio), arguing that applying the same €50,000 threshold to all foreign companies regardless of risk profile violated the proportionality principle under both Italian and EU law. After a hearing held on January 28, 2026, the TAR Lazio issued Ruling 4986/2026 dismissing the appeal on procedural grounds: the challengers had filed outside the 60-day deadline running from the publication of the December 2024 decree. The court did not rule on the merits of the proportionality argument, but no suspension was granted and the obligation has remained fully in force throughout. The practical message for any company still watching the litigation is straightforward — the legal window for challenge has closed, and compliance is the only viable path.
The Second Guarantee: The One Borne by Your Representative
A point that is often missed, because the two measures were adopted within days of each other: alongside the €50,000 guarantee owed by the foreign company, a separate Ministerial Decree of 9 December 2024 imposed good-standing requirements and a guarantee on the fiscal representative itself, scaled to the number of companies it acts for — from €30,000 for two to nine represented businesses up to €2,000,000 for more than a thousand, for a minimum of 48 months. The two guarantees are cumulative and serve different purposes. The practical effect for foreign groups has been a thinner market: fewer providers willing to act as fiscal representative, and higher fees from those that remain. It is a further argument for comparing the representative route against an Italian subsidiary before committing.
A Note for U.S. Companies
For U.S. businesses entering the Italian market or already holding Italian VAT registration through a fiscal representative, the guarantee requirement creates a concrete and recurring compliance cost. The annual premium for an insurance surety bond — the most commonly used form — typically falls between 1.5% and 4% of the guaranteed amount, translating to roughly €750 to €2,000 per year. This should be factored into Italian market-entry budgets. U.S. companies with existing VIES registrations that have not yet submitted the guarantee are exposed to deregistration at any time, which would immediately affect their ability to conduct zero-rated intra-EU transactions. Given the joint and several liability structure, non-compliance also creates reputational and financial risk for the Italian fiscal representative, which can strain an otherwise workable professional relationship.
Final Considerations
The €50,000 VIES guarantee has moved from a contested new regulation to settled law. For any non-EU company that sells goods or services cross-border within the EU via Italy, or that sources from EU suppliers using Italian VAT registration, implementation is now the only question on the table. Companies that have not yet complied should act without further delay. Those planning Italian market entry for the first time should build the guarantee requirement — and its ongoing cost — into their setup timeline from the outset. A qualified Italian tax adviser can identify the correct guarantee form, verify the submission requirements at the relevant Revenue Agency office, and coordinate with the fiscal representative to ensure the obligations are met correctly on both sides.

Italy’s Inheritance and Gift Tax Reform: What International Families Need to Know

Italy’s Inheritance and Gift Tax Reform: What International Families Need to Know

Italy has overhauled its rules on inheritance and gift taxation through two legislative decrees — Decree 139/2024 and Decree 123/2025 — with the most significant changes taking effect on January 1, 2026. For expats, foreign nationals with property in Italy, and international families with cross-border estate plans, the reform introduces both meaningful opportunities and new compliance obligations.
Tax Rates Are Unchanged — But the Thresholds Just Got Better
Italy’s headline inheritance and gift tax rates remain the same: 4% for transfers to spouses and direct descendants (children, grandchildren), 6% for siblings and other relatives up to the fourth degree, and 8% for unrelated beneficiaries. What changed is how the tax-free threshold — called the franchigia — is calculated.
Under the old system, a mechanism known as the coacervo required the tax authority to aggregate all lifetime gifts made to a beneficiary with whatever they ultimately received through inheritance. A child who received a €600,000 gift from a parent during their lifetime had only €400,000 of their €1 million threshold left when the parent died. This aggregation rule, abolished as of January 1, 2026, had long been criticised as penalising families who used gifting as part of their estate plan.
From 2026 onward, gifts and inheritances each carry their own separate €1 million threshold per qualifying beneficiary (spouse or direct descendant). A child can now receive up to €1 million in lifetime gifts and still benefit from a full €1 million threshold upon inheritance. For siblings, the separate thresholds stand at €100,000 each. In practical terms, this change doubles the potential tax-free transfer capacity between generations for families who use both instruments.
Trusts: Now Expressly Addressed in Italian Succession Law
For the first time, Italy’s succession tax legislation expressly addresses the treatment of trusts. Previously, the framework had developed through administrative circulars and case law, leaving considerable uncertainty for international structures.
The new rules confirm that transfers of assets via trust are subject to inheritance and gift tax whenever they result in a gratuitous enrichment of beneficiaries. Crucially, the reform gives trustees and settlors a planning choice: they may elect to trigger the tax at the time assets are contributed to the trust, or defer it until assets are distributed to beneficiaries. Where beneficiaries are not yet identified, the 8% rate — applicable to transfers between strangers — applies by default. Once the tax is paid at either stage, subsequent distributions in the same kinship category are not taxed again.
The territorial rules for trust taxation follow the settlor’s residency at the time assets are contributed to the trust, not at distribution. If the settlor was an Italian tax resident when the assets entered the trust, Italian succession tax applies to all transferred assets, wherever located. Non-resident settlors face Italian tax only on Italian-sited assets.
Self-Assessment Is Now the Taxpayer’s Responsibility
Another structural change affects how the tax is collected. Under the previous system, the Agenzia delle Entrate calculated the tax owed and issued a formal notice. The reform shifts this obligation to the taxpayer: heirs and beneficiaries must now calculate, declare, and pay the inheritance tax themselves, within 90 days of the succession opening. The tax authority retains a two-year window to challenge the calculation. Electronic filing is required in most cases, though non-resident heirs may still submit declarations by registered mail.
This change increases the importance of getting professional advice promptly after a death, since errors in self-assessment can lead to penalties.
Cross-Border Estates: Who Is Taxed on What
Italy’s territorial scope for inheritance tax follows the residence of the deceased at the time of death, not the location of the assets. If an Italian tax resident dies, their worldwide estate — including foreign bank accounts, foreign real estate, and financial investments held abroad — is subject to Italian succession tax. Conversely, if a non-resident dies but owned property in Italy, only the Italian assets are within scope. Beneficiaries who are themselves Italian residents must report and pay tax on all assets received from an Italian-resident decedent, regardless of where those assets are physically located.
There is no bilateral inheritance or estate tax treaty between Italy and most countries, including the United States. Families with assets in multiple jurisdictions should model the combined tax exposure carefully.
A Note for U.S. Citizens
U.S. citizens are subject to U.S. federal estate and gift tax on their worldwide assets, regardless of where they live. Unlike the Italy-U.S. income tax treaty, there is no Italy-U.S. estate and gift tax treaty. This means a U.S. citizen who is an Italian tax resident may face both Italian inheritance/gift tax and U.S. estate or gift tax on the same transfer, with limited mechanisms to avoid double taxation.
Italy’s rates — 4% to 8% — are substantially lower than the U.S. federal estate tax rate of 40% on amounts above the exemption. The U.S. does provide a foreign death tax credit under Section 2014 of the Internal Revenue Code for foreign estate taxes paid on assets that are also subject to U.S. estate tax, but this credit has specific limitations and does not always provide full relief. For gifts, the interaction is more complex: Italy now taxes certain gift transactions that the U.S. would treat as taxable gifts, but the tax systems operate independently.
U.S. citizens in Italy who hold assets in trust structures — particularly grantor trusts used in U.S. estate planning — should review how the new Italian trust taxation rules interact with their existing structures.
Final Considerations
The 2026 reform makes Italy’s succession tax framework more transparent and, for many families, more generous in terms of available exemptions. The abolition of the coacervo is a genuine planning improvement. At the same time, the shift to self-assessment raises the stakes for accurate compliance, and the new trust rules introduce mandatory analysis for anyone with a trust structure linked to Italy.
For international families — particularly those with assets, heirs, or residency ties in multiple countries — the practical impact of these changes depends heavily on individual circumstances. Professional advice is recommended before making gifts, establishing trusts, or updating cross-border estate plans in light of the new framework.

Italy’s 2026 Crypto Tax: What the 33% Rate Means for Residents and Expats

Italy’s 2026 Crypto Tax: What the 33% Rate Means for Residents and Expats

Italy’s approach to taxing digital assets has shifted decisively with the 2026 Budget Law. The changes are significant enough that anyone living in Italy who holds cryptocurrency — or who is considering moving to Italy and has crypto holdings — needs to understand the new rules before the current tax year produces taxable events.

The New 33% Capital Gains Rate

From January 1, 2026, capital gains on most crypto-assets — including Bitcoin, Ether, and dollar-denominated stablecoins such as USDT and USDC — are subject to a 26% substitute tax that was already in place since 2023. That rate has now been raised to 33%. The increase was introduced by the 2026 Budget Law and applies to all disposal events: selling crypto for euros or other fiat currency, swapping one crypto for another, and using crypto to pay for goods or services.

The 33% rate aligns crypto gains more closely with the tax treatment of other speculative financial income under Italian law, a clear signal of the government’s intention to treat digital assets as a permanent and fully taxed asset class.

The €2,000 Threshold Is Gone

Until the end of fiscal year 2024, Italian tax residents could realize crypto gains of up to €2,000 per year without owing tax. That exemption was abolished from fiscal year 2025 onward. It does not return in 2026. Every euro of realized gain is now taxable, regardless of how small the transaction.

For occasional holders who previously relied on staying below the threshold, this change demands attention even for modest portfolio activity.

Euro Stablecoins: A Lower Rate

The 2026 Budget Law creates a specific carve-out for electronic money tokens (EMTs) — digital instruments that maintain a fixed parity with the euro and are issued under the EU’s MiCAR regulation. These include euro-denominated stablecoins such as EURC and EURS. Capital gains on these instruments are taxed at 26% rather than 33%, a meaningful difference for traders who regularly move between volatile assets and stable reserves.

Dollar-pegged stablecoins do not qualify. The preferential rate is limited to euro-denominated tokens that meet MiCAR’s reserve and licensing requirements.

The 18% Redetermination Option

The Budget Law also offers a one-time option to redetermine the cost basis of crypto holdings as of January 1, 2026 by paying an 18% substitute tax on the portfolio’s value at that date. This effectively resets the acquisition cost to the current market value, reducing the taxable gain on any future sale. For long-term holders sitting on large unrealized gains, this can substantially reduce the effective tax burden when they eventually sell — though it requires paying the 18% charge upfront.

The decision of whether to exercise this option requires calculating the likely future gain against the immediate cost, and it is most attractive when the existing cost basis is very low relative to current value.

Reporting: Quadro RW and Quadro RT

Italian tax residents must report foreign-held crypto assets in Quadro RW of the Redditi PF return. This form is used both for monitoring purposes and, in many cases, for calculating the IVAFE wealth tax on financial assets held abroad. The applicable IVAFE rate and whether it applies to crypto assets held on foreign platforms should be confirmed for each specific situation, as the rules in this area have been subject to revision. Where assets are held on Italian-licensed platforms, reporting requirements may differ.

Quadro RT is used to declare capital gains and losses. Losses can be carried forward to offset gains in the following four tax years, provided they are declared in the year they arise.

Failure to complete either form carries substantial penalties: non-reporting of foreign assets can result in penalties of 3% to 15% of the undisclosed amount, in addition to fixed sanctions.

A Note for U.S. Citizens

On the U.S. reporting side, crypto held on foreign exchanges may qualify as a specified foreign financial asset under FATCA, requiring disclosure on Form 8938 if aggregate foreign financial assets exceed the applicable filing threshold ($50,000 for individuals filing a return in the United States). FBAR reporting for foreign crypto accounts remains a developing area: FinCEN has signaled its intention to extend FBAR requirements to foreign virtual asset accounts, and U.S. citizens should monitor this closely given proposed rules currently pending finalization.

The combination of Italian income tax, potential IVAFE on foreign-held assets, U.S. federal tax obligations, and parallel reporting requirements under both systems makes cryptocurrency one of the more complex compliance areas for U.S. nationals in Italy.

Final Considerations

The 2026 changes mark a clear shift toward treating crypto-assets as mainstream financial instruments under Italian law, with the rates and reporting requirements now reflecting that approach. The abolition of the €2,000 exemption and the increase to 33% mean that even moderate holders face meaningful tax obligations that did not exist under prior rules.

Anyone with Italian tax residency and crypto holdings should review their position, confirm their cost basis documentation, and evaluate whether the 18% redetermination option makes sense in their individual circumstances. The interaction between Italian and foreign tax obligations — particularly for U.S. citizens — adds further layers that are best addressed with professional advice before the end of the tax year.

Foreign Assets and Italian Tax Residency: A Practical Guide to Quadro RW, IVAFE, and IVIE

Foreign Assets and Italian Tax Residency: A Practical Guide to Quadro RW, IVAFE, and IVIE

Becoming an Italian tax resident does not only affect how your income is taxed — it also triggers a set of obligations relating to assets you continue to hold abroad. Anyone who transfers their tax residency to Italy and retains a foreign bank account, investment portfolio, property, or equity stake must comply with Italy’s foreign asset monitoring and wealth tax framework. Failing to do so carries significant penalties. This article provides a practical overview of what is required and what it costs.

The Monitoring Obligation: Quadro RW

Every Italian tax resident who holds financial or non-financial assets outside Italy at any point during the tax year must disclose them in Quadro RW, a dedicated section of the Italian personal income tax return. The purpose is twofold: it gives the tax authorities visibility over assets held offshore, and it serves as the basis for calculating the two wealth taxes described below.

Assets subject to disclosure include foreign bank and deposit accounts, brokerage accounts, stocks and bonds held outside Italy, shares in foreign companies, investment funds domiciled abroad, foreign real estate, foreign pension accounts, cryptocurrencies held on foreign platforms, and precious metals or valuables kept outside Italian territory. The list is broad, and the Italian Revenue Agency interprets it expansively.

The reporting threshold for foreign bank accounts is an average annual balance exceeding €5,000. In practice, however, any account that at any point during the year exceeds a daily balance of €15,000 must also be reported for monitoring purposes, even if the average stays below the threshold. For all other financial assets — securities, funds, equity interests — there is no minimum threshold: they must be reported regardless of value.

Until recently, Quadro RW was only available in the longer Redditi PF form, which many employed workers were not required to file. From the 2024 tax period onward, the equivalent section — Quadro W — has been incorporated into the simplified 730 form, making compliance accessible to a broader group of taxpayers, including employees and pensioners.

IVAFE: Wealth Tax on Foreign Financial Assets

IVAFE (Imposta sul Valore delle Attività Finanziarie Estere) is an annual wealth tax levied on financial assets held abroad. The standard rate is 0.2% per year, applied to the market value of the assets as at 31 December of the relevant tax year, or the average value where no year-end market price is available.

For foreign current and savings accounts, the tax is calculated differently: a flat charge of €34.20 per account per year applies, rather than a percentage. IVAFE on bank accounts is not due if the average annual balance does not exceed €5,000.

Assets held in or through jurisdictions on Italy’s list of non-cooperative tax territories are subject to a higher rate of 0.4% — double the standard charge. This applies where the financial intermediary or the asset itself is located in a blacklisted country.

IVAFE is calculated and paid through the annual tax return. A credit is available for any similar wealth taxes paid to a foreign government on the same assets, avoiding outright double taxation — though the mechanics of the credit vary depending on the country and the nature of the asset.

IVIE: Wealth Tax on Foreign Real Estate

IVIE (Imposta sul Valore degli Immobili situati all’Estero) is the equivalent charge applied to real estate owned outside Italy. Since the 2024 tax year, the rate has been 1.06% per year, following an increase from the previous 0.76% introduced by the 2024 Budget Law.

The taxable base is generally the purchase price of the property, or its cadastral value if available in the relevant foreign country. Where neither is available, the market value at the relevant date is used. A reduced rate of 0.40% applies to property used as the taxpayer’s principal residence abroad, with a €200 deduction.

As with IVAFE, a credit is available for property taxes paid in the country where the real estate is located, which in many cases eliminates or substantially reduces the Italian charge.

Penalties for Non-Compliance

The consequences of failing to file Quadro RW are material. For assets held in EU or EEA countries, the penalty ranges from 3% to 15% of the undisclosed asset value. For assets held in non-EU countries, the range rises to 6% to 30%. Where the country involved is on Italy’s list of non-cooperative jurisdictions, penalties are doubled again. In addition, the statute of limitations for undisclosed foreign assets is extended beyond the ordinary term, giving the Revenue Agency more time to raise assessments.

A Note for U.S. Citizens

U.S. citizens living in Italy face a parallel disclosure system on top of the Italian obligations. FBAR (FinCEN Form 114) requires reporting any foreign financial account to the U.S. Treasury if the aggregate value of all foreign accounts exceeds $10,000 at any point during the calendar year. Form 8938 (FATCA) requires disclosure of specified foreign financial assets above thresholds that vary by filing status and residency. Both obligations exist independently of Quadro RW — the same accounts and assets may need to be reported in all three filings. The Italian and U.S. systems do not exchange information automatically in a way that substitutes for compliance on either side.

Final Considerations

For anyone who has recently moved to Italy and retains assets abroad — whether a bank account in their home country, a brokerage account, a pension fund, or a property — the RW obligation applies from the first year of Italian tax residency. The interaction between IVAFE, IVIE, and any foreign wealth taxes already paid requires careful calculation. Professional advice is strongly recommended before filing, particularly for complex asset structures or assets held in non-EU jurisdictions.

Impatriati Regime: Moving from Southern to Northern Italy Has Retroactive Tax Consequences

Impatriati Regime: Moving from Southern to Northern Italy Has Retroactive Tax Consequences

Italy’s inbound workers tax regime (regime degli impatriati) offers significant income tax relief to professionals and employees who transfer their residency to Italy after a qualifying period abroad. For those who settle in one of Italy’s southern regions, the benefit is even greater — but a ruling issued by the Italian Revenue Agency in March 2026 makes clear that relocating north mid-way through the relief period comes at a cost, and that cost runs backwards in time.

The Enhanced Benefit for Southern Regions

Under the rules applicable to workers who returned to Italy before 2024, the standard impatriati regime exempts 70% of qualifying income from IRPEF — meaning only 30% is subject to ordinary income taxation. For workers who transfer their residency to one of eight specified southern regions (Abruzzo, Molise, Campania, Puglia, Basilicata, Calabria, Sardinia, and Sicily), the exemption rises to 90%, with only 10% of qualifying income taxed. This enhanced relief was designed not just to attract workers to Italy, but to channel them specifically into regions where the economy needs a boost.

The legislation conditions this 90% rate on one key requirement: the worker must maintain residency in the qualifying southern region for the entire five-year duration of the benefit. What happens if they don’t was, until recently, less clear in practice.

What Ruling 76/2026 Decides

The case underlying the ruling involved a professional who returned to Italy in 2023 and established residency in Puglia, applying the 90% exemption from the outset. In 2024 they began a new employment with a Rome-based employer, and in 2025 they transferred their registered residency to Lazio. They asked the Revenue Agency three questions: does the move end all impatriati benefits, when exactly does the change take effect, and must prior years be corrected?

The Agency’s answer, issued on 11 March 2026, addresses all three points.

On the first question, the news is positive: moving to a non-qualifying region does not terminate the entire impatriati regime. The worker retains the standard 70% exemption for the remaining years of their five-year window. Only the enhanced 90% tier is lost.

On the second and third questions, the answer is considerably harsher. The Agency holds that the loss of the 90% benefit does not operate only from the date of the move, nor only for future tax years. It applies retroactively from the very first year of Italian residency. The reasoning is that the enhanced rate was never truly earned: the legislation requires uninterrupted southern residency throughout the entire benefit period, and since that condition was not ultimately met, the taxpayer never had the right to the 90% rate in the first place.

The Practical Consequence: Amending Prior Returns

For the worker in the ruling, this means the 90% rate applied to 2023 — the year of return, when they genuinely lived in Puglia — must be unwound. An amended tax return (dichiarazione integrativa) is required for that year, recalculating taxable income at the 30% standard level rather than the 10% enhanced level. The resulting additional tax, plus interest and penalties under Art. 1, comma 2, D.Lgs. 471/1997, must be paid. The voluntary disclosure mechanism (ravvedimento operoso) is available if the conditions are met, which can reduce the penalties.

The Agency adds a further, final point: a subsequent move back to a southern region would not restore the 90% exemption. What matters is continuous and unbroken residency in a qualifying region from the moment of first return. Once that continuity is broken, it cannot be reconstructed.

A Note for U.S. Citizens

U.S. citizens who applied the 90% exemption and claimed Italian taxes paid as a Foreign Tax Credit on their U.S. returns will need to consider the knock-on effect. Amending an Italian return to report higher taxable income and pay more Italian tax also means revisiting the U.S. returns for the relevant year — the FTC calculation will change. Depending on the amounts involved and whether the taxpayer was in an excess credit or excess limitation position, the U.S. tax impact could go in either direction. Professional advice covering both jurisdictions is essential before filing any amended return.

Final Considerations

Ruling 76/2026 draws a strict line: the enhanced southern-region benefit is all-or-nothing over the full five years. Workers who chose their Italian location partly with the 90% exemption in mind should treat any planned internal relocation as a tax event requiring prior analysis, not just a change of address. If a move north is under consideration, calculating the retroactive adjustment and the cost of regularising prior years before committing is strongly advisable. A specialist review at the planning stage is far less costly than correcting the position after the fact.

Intra-Group Service Costs in Italy: What the 2026 Cassazione Ruling Means for Multinational GroupsItaly’s

Intra-Group Service Costs in Italy: What the 2026 Cassazione Ruling Means for Multinational Groups


Italy’s Supreme Court has issued a landmark ruling that significantly tightens the conditions under which Italian companies within multinational groups may deduct costs charged by parent or affiliate entities. The decision — Cassazione n. 5753 of 13 March 2026, involving an Italian subsidiary of Shell — confirms and reinforces a demanding standard that applies to any company operating in Italy as part of a corporate group.
The Core Principle: Inerenza
Under Article 109 of the Italian Consolidated Income Tax Act (TUIR), a cost is only deductible if it is inerente — that is, genuinely relevant and connected to the income-generating activity of the Italian entity claiming the deduction. This is not a technicality; it is the foundational gatekeeper for any business expense deduction in Italy.
For intra-group charges, the principle operates with particular rigour. The mere existence of a cost-sharing agreement, an intercompany contract, or paid invoices is not enough. The Italian company must demonstrate that the services charged actually served its own business operations and produced — or were objectively capable of producing — a real economic benefit for the recipient.
The Benefit Test: What You Must Prove
The Cassazione in ruling n. 5753/2026 confirmed that the burden of proof falls entirely on the Italian subsidiary. To sustain the deduction, the company must be able to show:

-the precise nature and scope of the services received;
-that those services were actually performed and delivered to the Italian entity (not merely invoiced);
-the real and quantifiable benefit the subsidiary derived from them;
-adequate documentation of the associated costs and payments.

It is not sufficient to say that services formed part of a group-wide programme or that the parent’s overhead was allocated on a pro-rata basis. The Italian entity must be able to establish concretely what it received and why that service was useful to it specifically.
Shareholder Activities: What Cannot Be Recharged
A critical distinction confirmed by the ruling — and consistent with the OECD Transfer Pricing Guidelines — is the treatment of shareholder activities. These are services that the parent company performs in its own interest as a shareholder: strategic group oversight, corporate governance, consolidated accounting, group-level brand management, and similar activities that serve the structure as a whole rather than any particular subsidiary.
According to settled Italian case law and OECD guidance, these costs cannot legitimately be recharged to subsidiaries. They respond to the needs and interests of the parent, not those of the Italian entity. Including such charges in an intercompany cost allocation without adequate segregation exposes the entire set of deductions to challenge.
The Temporal Competence Issue
The ruling also reaffirmed the non-derogable nature of temporal competence rules under Italian law. A company cannot elect to claim a deduction in a different tax year to manage its tax results. Costs must be recognised and deducted in the period to which they economically belong. Attempting to absorb prior-year charges into a more convenient year — outside of the formal procedures for amended returns or refund claims — will not be accepted by the tax authorities or the courts.
Practical Implications for Group Companies in Italy
Any Italian entity that is part of a multinational group — whether the Italian operation is a subsidiary, a branch, or a principal structure — should review its intercompany arrangements in light of this ruling. The key risk areas are: cost-sharing agreements where the benefit to the Italian entity is not clearly documented; management fee structures where operational services and shareholder activities are not clearly separated; and historical deductions claimed under arrangements that pre-date current documentation standards.
The Revenue Agency has consistently challenged intra-group cost deductions where documentation is generic, and the courts have continued to uphold that approach. Ruling n. 5753/2026 gives added judicial weight to this line of enforcement.
A Note for U.S. entities
U.S. persons who own or manage Italian subsidiaries through U.S. parent entities face a layered compliance picture. On the Italian side, the rules described above apply fully. On the U.S. side, the IRS has its own transfer pricing regime under Section 482 of the Internal Revenue Code, which requires intercompany charges to reflect arm’s length pricing and to be supported by contemporaneous documentation. Where an Italian subsidiary is disallowed a deduction because the benefit test is not met, this can also affect the U.S. parent’s consolidated tax position, including the treatment of any income received as a management fee. U.S.-owned groups operating in Italy should ensure that their Italian transfer pricing documentation and their U.S. Section 482 documentation are aligned and mutually consistent. Specialist advice on both sides is strongly recommended.
Final Considerations
Ruling n. 5753/2026 does not introduce new law, but it consolidates and sharpens a rigorous judicial standard that Italian tax authorities are actively applying. For multinational groups with Italian operations, the message is clear: intercompany cost arrangements must be backed by substance, specificity, and contemporaneous documentation — not just contracts and invoices. Companies that review and strengthen their documentation now, and that clearly separate operational service charges from shareholder-level overhead, will be in a significantly stronger position in the event of an audit. Given the complexity of these issues, professional advice tailored to the group’s specific structure is essential.

Working Remotely for a Foreign Employer? Italy’s Impatriati Regime Now Officially Applies

Working Remotely for a Foreign Employer? Italy’s Impatriati Regime Now Officially Applies

One of the most frequent questions we receive from professionals considering a move to Italy is whether the impatriati regime — Italy’s 50% income tax exemption for inbound workers — applies when their employer is based abroad and they plan to work from home in Italy. In January 2026, the Italian Revenue Agency answered that question clearly.

The Ruling: Location of Work, Not of Employer

The Revenue Agency confirmed that the impatriati regime is fully available to employees who transfer tax residence to Italy and continue working remotely for a foreign employer, provided the activity is carried out predominantly from Italian territory. The principle is straightforward: what counts is where the work is actually performed, not where the employer is located. If you live and work in Italy — even if your contract is governed by foreign law or your payslips come from a company headquartered abroad — you can claim the 50% IRPEF exemption on your qualifying income for five years. This applies to the new impatriati regime in force since 2024. Qualifying workers who transfer residence to Italy can exclude 50% of their Italian-source employment or self-employment income from IRPEF, up to €600,000 per year, for five consecutive tax years.

Key Requirements

Under the reformed regime, the worker must transfer Italian tax residence and not have been resident in Italy for at least the three years immediately preceding the transfer. A degree (bachelor level or equivalent) is required for highly qualified or specialised roles. Work must be performed predominantly in Italy, meaning more than 183 days per year physically working from Italian territory. Notably, the new regime no longer requires the old “functional link” between the transfer of residence and the start of the qualifying work activity — making it easier for workers who return to Italy independently of any job change.

A Note for U.S. Citizens

U.S. citizens are taxed by the United States on their worldwide income regardless of where they live. Moving to Italy and claiming the impatriati exemption does not reduce the U.S. tax bill directly. However, Italian income taxes paid should in principle generate Foreign Tax Credits against U.S. liability — though the precise mechanics depend on how the income is characterised and on the applicable treaty provisions. U.S. citizens in this situation should seek advice from a professional experienced in both Italian and U.S. taxation before assuming the credits will offset in full.

Practical Points

Remote workers should keep records to demonstrate they worked predominantly from Italian territory: diary entries, travel records, and any documentation from the employer confirming the remote arrangement. If the foreign employer does not apply Italian payroll withholding, the worker self-declares the income and the impatriati exemption in their Italian annual tax return — the Revenue Agency has confirmed this is the standard approach. One consideration for employers: if a senior employee habitually concludes contracts on behalf of a foreign company from Italian soil, that company could inadvertently create a taxable presence in Italy. This is a corporate structuring question the employer’s own advisers should evaluate.

Final Considerations

The ruling removes a practical ambiguity that had discouraged many remote professionals from claiming a benefit they were entitled to. For professionals already resident in Italy and working remotely for a foreign employer — or planning such a move — the five-year clock starts from the first year of Italian tax residence, so timing matters. As always, cross-border situations require coordinated advice. The Italian regime is generous, but it does not operate in isolation from a taxpayer’s home-country obligations.

Italy’s Non-Dom Flat Tax Just Got More Expensive: What the €300,000 Lump Sum Means for New Residents in 2026


Italy’s new-resident lump sum tax regime — one of the most generous non-domicile regimes in Europe — has become significantly more expensive for anyone moving to Italy from 1 January 2026. The country’s 2026 Budget Law raised the annual substitute tax from €200,000 to €300,000, and doubled the charge for qualifying family members from €25,000 to €50,000 each. For high-net-worth individuals considering a move to Italy, this change reshapes the planning calculus — though it does not eliminate the regime’s substantial advantages.

What the Regime Offers

Introduced in 2017 under Article 24-bis of the Italian Tax Code (TUIR), the regime allows individuals who have not been Italian tax residents for at least nine of the previous ten years to replace ordinary Italian taxation on all foreign-source income with a single annual lump-sum payment. That payment is now €300,000 per year, irrespective of how much foreign income was actually earned. A British executive receiving £1 million per year in dividends from a UK holding company and a retired American collecting $80,000 in U.S. investment income both pay the same flat amount — provided they qualify.

The regime lasts for a maximum of 15 years. During that period, participants are also exempt from IVIE (the Italian wealth tax on foreign real estate) and IVAFE (the Italian wealth tax on foreign financial assets), and they have no obligation to disclose foreign assets in the annual Italian tax return. Foreign assets transferred by gift or inheritance are not subject to Italian inheritance or gift tax — only Italian-situated assets remain within scope.

Italian-source income, however, is taxed under ordinary Italian rules and is not covered by the regime.

Three Tiers, Three Cohorts

The evolution of the regime has produced three distinct cohorts of taxpayers, each grandfathered at the rate applicable when they opted in:

Individuals who established Italian tax residence and opted into the regime before 10 August 2024 continue to pay €100,000 per year for the remainder of their 15-year term. Those who opted in between 10 August 2024 and 31 December 2025 pay €200,000 per year. Anyone who transfers Italian tax residence on or after 1 January 2026 is subject to the new €300,000 rate.

Italy has consistently respected the grandfathering principle across these changes: no existing participant has been required to pay more than the amount in force at the time they opted in. This is a meaningful commitment — and one potential entrants should factor into their timing decisions.

How to Qualify and Apply

Eligibility rests on one primary condition: the individual must not have been an Italian tax resident in at least nine of the ten tax years immediately preceding their transfer to Italy. Nationality is irrelevant — U.S. citizens, UK nationals, and third-country nationals all qualify on the same basis.

The option is exercised through the Italian income tax return for the first year of Italian tax residence (or, in some cases, through a prior ruling request to the Italian Revenue Agency). Timely payment of the substitute tax by 30 June each year is an essential condition: failure to pay terminates the regime. There is no possibility of partial payment or instalment.

Family members can be included under the regime, each subject to a separate €50,000 annual charge. “Family members” for this purpose generally means spouses and dependent children, though the perimeter should be confirmed on a case-by-case basis.

The U.S. Angle: A Crucial Caveat

For U.S. citizens, the regime works differently than for most other nationalities — and the difference matters. The United States taxes its citizens on worldwide income regardless of where they live. A U.S. citizen who pays €300,000 to Italy under the lump sum regime will still owe U.S. tax on all foreign-source income under IRS rules. The Italian substitute tax is not a foreign tax credit eligible for offset against U.S. income tax in the normal way, because it is a lump sum, not a tax computed on the income itself.

This does not make the regime useless for Americans, but it does mean the analysis requires careful modelling. In practice, the regime is most advantageous for U.S. citizens with very large amounts of foreign income — where the €300,000 flat charge is modest relative to what Italian progressive rates (up to 43%) would otherwise produce — and who can structure their U.S. position efficiently. Any U.S. citizen considering the regime should obtain specialist U.S. tax advice alongside Italian advice.

For UK nationals, the picture has also changed. The abolition of the UK non-domicile regime in April 2025 removed a longstanding alternative. Italy’s lump sum regime is now one of the few credible non-dom frameworks available to UK-resident HNWIs looking to relocate, alongside Malta and Portugal. The higher €300,000 cost reduces its attractiveness at the margin, but the combination of lifestyle, the 15-year horizon, and the inheritance tax shelter on foreign assets still makes Italy competitive for those with substantial non-Italian wealth.

Is the Higher Cost Still Worth It?

At €300,000 per year, the break-even point relative to ordinary Italian taxation has moved. Under standard Italian rates, €300,000 per year in tax corresponds roughly to a taxable income of approximately €800,000 to €900,000, depending on deductions. For individuals with foreign income well above that level, the regime continues to offer substantial savings. For those with foreign income in the €300,000–€600,000 range, the calculation is more delicate and depends on income type, applicable treaties, and individual circumstances.

What the regime continues to offer that no standard tax position can replicate is certainty and simplicity: one annual payment, no ordinary IRPEF computation on foreign income, no IVIE or IVAFE filings, and no foreign asset disclosure.

Final Considerations

The €300,000 lump sum regime remains one of the most attractive non-domicile frameworks available in Europe, despite its increased cost. For high-net-worth individuals with substantial foreign income — particularly investment portfolios, passive business income, or real estate returns outside Italy — the regime can deliver significant tax savings and meaningful administrative simplicity over a 15-year horizon.

The grandfathering principle also creates a window of opportunity for individuals who are already planning a move to Italy but have not yet formalised their tax residence: the €200,000 rate is definitively closed, but understanding the rules, timing the transfer correctly, and filing the option accurately in the first tax year are all critical steps that require professional guidance.

U.S. citizens face additional layers of complexity due to U.S. citizenship-based taxation, and should not assume that the Italian treatment resolves their U.S. obligations. UK nationals navigating post-non-dom planning may find Italy’s framework worth serious consideration, but the comparison with other jurisdictions should be made with up-to-date advice on each.